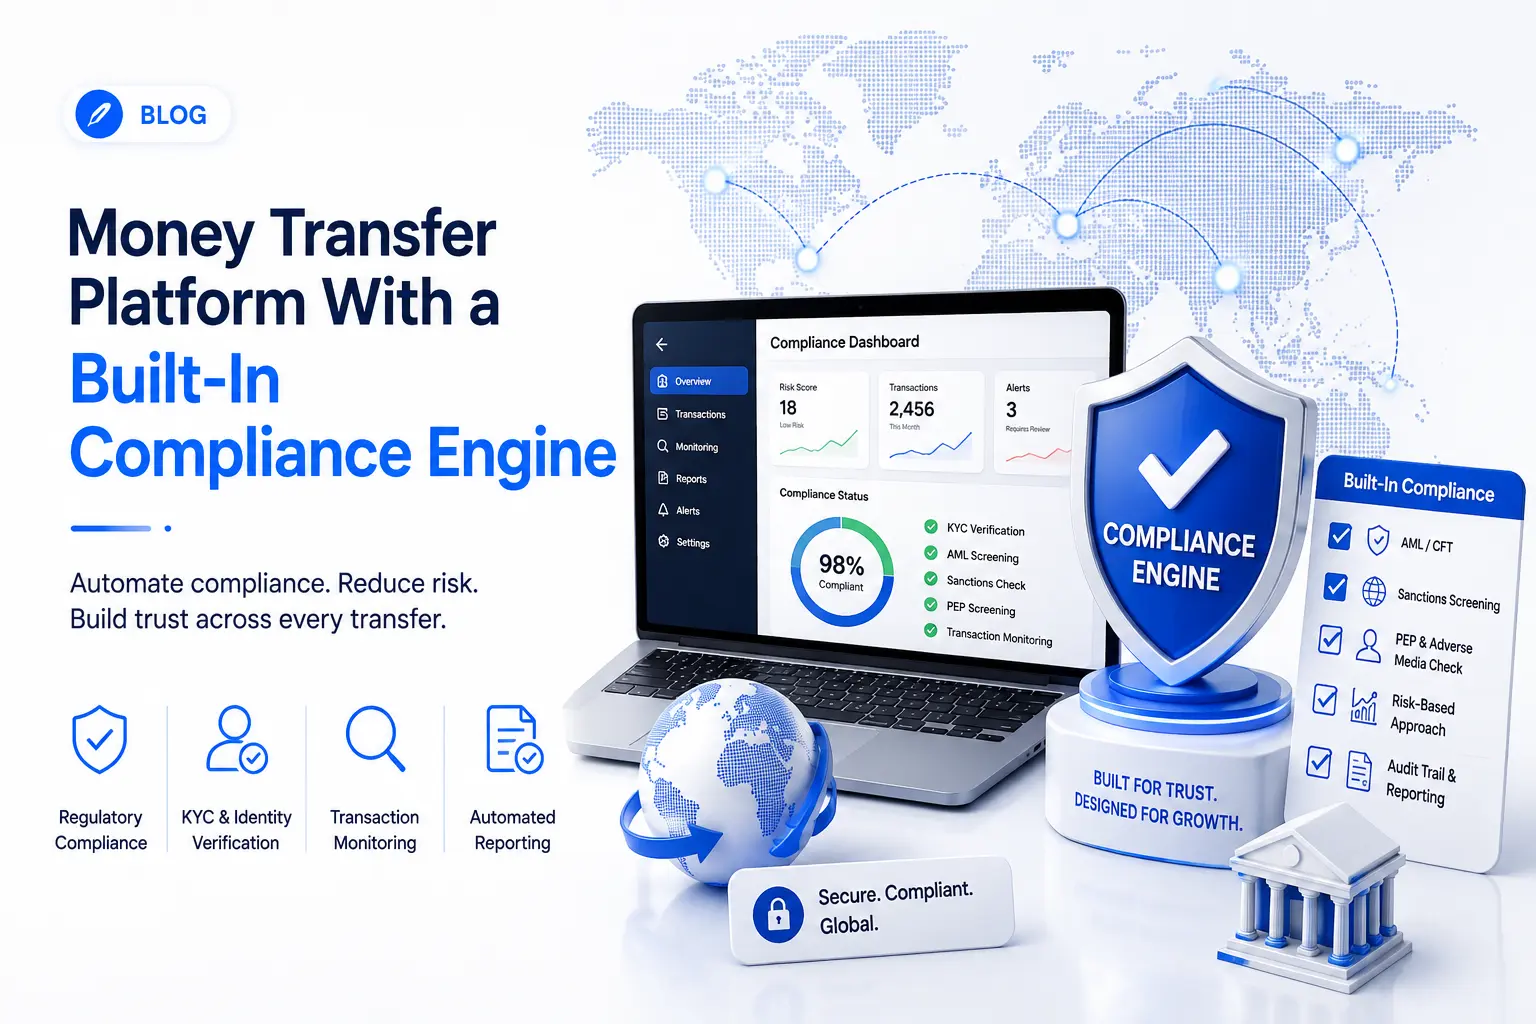
Money Transfer Platform With a Built-In Compliance Engine
Why a modern money transfer platform needs compliance capabilities connected to the customer and transaction lifecycle.
Building a money transfer business can look deceptively simple.
You create an app, allow customers to enter the amount they want to send, connect a payment provider, and transfer the money to a recipient.
But once you move from the idea to the actual technology architecture, the picture changes quickly.
You need customer onboarding, identity verification, KYC, AML screening, sanctions checks, transaction monitoring, exchange-rate management, payment processing, payout connectivity, administration tools, notifications, reporting, security, infrastructure and ongoing maintenance.
And every component has to work together.
So the question for a new Money Transfer Operator (MTO) isn't simply:
“Can we build a remittance platform ourselves?”
Of course you can.
The better question is:
“Should we spend our time building the technology infrastructure, or should we focus our resources on building the remittance business?”
Building a remittance platform from scratch gives you maximum control, but it also means taking responsibility for designing, developing, integrating, securing and maintaining every major technology component.
For businesses entering the remittance market, a white-label money transfer software such as RemitSo can provide an existing technology foundation covering customer applications, administration, KYC/AML workflows, FX management, transaction processing and payment/payout connectivity.
This allows the business to focus more of its resources on customers, corridors, partnerships, pricing and growth rather than rebuilding common remittance infrastructure.
In This Article
- A Remittance Platform Is Much More Than an App
- What Happens When You Build Everything Yourself?
- The Hidden Cost Isn't Just Development
- The Integration Problem Gets Bigger as You Grow
- Compliance Cannot Be an Afterthought
- Then There Is the FX and Pricing Layer
- Building From Scratch Can Distract From the Actual Business
- So What Does a White-Label Platform Change?
- Your Brand Still Comes First
- You Can Start With One Corridor
- When Does Building From Scratch Actually Make Sense?
- When Does White-Label Make More Sense?
- The Real Question Isn't “Build or Buy”
- Build the Business, Not the Plumbing
- What RemitSo Provides
- Ready to Build Your Money Transfer Business?
- Frequently Asked Questions
A Remittance Platform Is Much More Than an App
One of the biggest mistakes new founders make is thinking of a remittance platform as a mobile application.
The app is only the customer-facing layer.
Behind it is an entire operational system.
A typical remittance technology stack can include:
| Technology Layer | What It Needs to Handle |
|---|---|
| Customer App | Registration, login, beneficiaries, transfers and tracking |
| Web Portal | Customer access and transaction management |
| Admin Dashboard | Customers, transactions, rates, fees and operations |
| KYC/KYB | Identity and business verification |
| AML | Risk controls and transaction monitoring |
| Sanctions Screening | Screening customers and relevant parties |
| FX Engine | Exchange rates, spreads and pricing |
| Payment Integration | Collecting funds from customers |
| Payout Integration | Delivering funds to recipients |
| Notifications | Email, SMS, push and transaction updates |
| Reporting | Operational and compliance reporting |
| Infrastructure | Servers, databases, APIs, monitoring and security |
| Support Tools | Transaction investigation and customer support |
Building all of this is a very different project from building an app.
What Happens When You Build Everything Yourself?
Let's imagine you decide to build your own platform.
You hire developers.
The first requirement might be simple:
“We need an Android and iOS application.”
Then the requirements begin expanding.
You need:
- Registration and authentication
- Customer profiles
- Beneficiary management
- Transfer creation
- Transaction status
- Payment processing
- Exchange-rate calculation
- Fee calculation
- KYC verification
- AML screening
- Sanctions screening
- Transaction monitoring
- Admin controls
- Payout processing
- Notifications
- Reporting
- Audit logs
- API integrations
- Security controls
Suddenly, the project isn't an app.
It is a financial technology infrastructure project.
And the development doesn't end when the first version goes live.
Build Your Remittance Business on a Stronger Technology Foundation
Instead of recreating every standard remittance component, start with infrastructure designed around the operational needs of an MTO.
- Branded customer applications
- KYC and AML workflows
- FX and pricing management
- Payment and payout connectivity
- Transaction management
- Administration and operations
The Hidden Cost Isn't Just Development
The biggest misconception about building from scratch is calculating only the initial development cost.
The real cost includes everything that happens afterward.
Development
You need engineers to build the platform, APIs, databases, applications and administration tools.
Integrations
Your platform may need to integrate with multiple third-party providers for:
- KYC
- AML
- sanctions
- payments
- payouts
- banking
- FX
- notifications
Each integration introduces additional development and testing requirements.
Security
A financial platform cannot treat security as an optional feature.
You need appropriate authentication, authorization, encryption, secure APIs, infrastructure controls, monitoring and ongoing security maintenance.
Maintenance
Third-party APIs change.
Payment providers change requirements.
Operating systems change.
Browsers change.
Security vulnerabilities are discovered.
New compliance requirements emerge.
Your platform therefore becomes a permanent engineering responsibility.
The Integration Problem Gets Bigger as You Grow
Imagine launching with one corridor.
For example:
USA → India
You might have one payment configuration and one payout network.
Then your customers ask for:
USA → Bangladesh
Then:
Canada → India
Then:
Australia → India
Then:
UK → Nigeria
Your technology requirements begin expanding with every corridor.
Different countries can introduce different:
- Payment methods
- Payout methods
- Currency requirements
- Banking requirements
- Regulatory considerations
- Partner APIs
- Operational workflows
Your engineering team now has to maintain the growing integration ecosystem.
This is one reason remittance technology can become increasingly complex as the business expands.
Compliance Cannot Be an Afterthought
A remittance business also needs technology that supports its compliance operations.
Depending on the jurisdiction and business model, this can involve areas such as:
- Customer identification
- KYC/KYB
- AML controls
- Sanctions screening
- PEP screening
- Transaction monitoring
- Risk assessment
- Case management
- Audit trails
- Regulatory reporting workflows
The important point is that these capabilities should not sit completely outside the transaction flow.
They need to interact with the customer and transaction lifecycle.
For example:
Customer onboarding → Identity verification → Risk assessment → Transaction → Screening → Monitoring → Review
If you're building the entire platform yourself, you also need to design how these systems communicate with one another.
Reduce the Engineering Work Behind Every New Corridor
Connect the customer journey, compliance controls, transaction processing, FX and partner integrations through a technology foundation built for remittance operations.
- Customer and transaction workflows
- Compliance and monitoring
- FX and pricing controls
- Payment integrations
- Payout connectivity
- Operational administration
Then There Is the FX and Pricing Layer
A remittance business isn't simply moving money from one country to another.
You also need to determine:
How much does the customer pay?
What exchange rate does the customer receive?
What fee does the business charge?
What FX margin does the business apply?
This means your platform needs pricing and exchange-rate functionality.
A basic flow might look like:
Market Rate → Platform Rate → FX Margin → Customer Rate → Transfer Amount
You may also need different pricing rules for different corridors, currencies, customer segments or transaction volumes.
Again, this is another system that has to interact with the rest of the platform.
Building From Scratch Can Distract From the Actual Business
This is perhaps the most important consideration.
Your competitive advantage may not be your ability to write APIs.
It may be:
- Understanding a particular customer community
- Having distribution in a market
- Having strong payout relationships
- Offering better pricing
- Building trust
- Providing better customer service
- Owning a valuable remittance corridor
- Having a strong brand
Imagine a founder has identified a strong opportunity for:
Australia → India
The founder could spend the next year building:
App → Admin → KYC → AML → FX → Payments → Payouts → Monitoring → Infrastructure
Or they could focus much more heavily on:
Customers → Partnerships → Corridor → Pricing → Acquisition → Operations
That is the strategic decision.
So What Does a White-Label Platform Change?
A white-label platform changes the starting point.
Instead of beginning with an empty development environment, you begin with an existing remittance technology foundation.
With RemitSo, for example, the technology layer is designed around the needs of money transfer businesses. See the money transfer platform for an overview of the platform.
That includes areas such as:
- Branded customer applications
- Web experience
- Administration
- Customer management
- KYC/KYB workflows
- AML and sanctions workflows
- Transaction monitoring
- FX and rate management
- Fees and pricing
- Payment integrations
- Payout connectivity
- Transaction management
- Operational workflows
The business can then configure the platform around its own market, brand and operating model.
Your Brand Still Comes First
Using a white-label platform doesn't mean customers have to know you're using someone else's technology.
The purpose of white-label infrastructure is the opposite.
The customer experience can be presented around your brand.
Your:
- Logo
- Brand identity
- Customer application
- Website
- Pricing
- Customer relationships
- Marketing
- Support
RemitSo operates as the technology layer behind the business.
The customer sees your remittance company.
You Can Start With One Corridor
You don't necessarily need to build a global remittance business on day one.
A more focused approach can be:
Step 1 — Identify your market
Who are you serving?
Step 2 — Identify the corridor
Where are your customers sending money?
Step 3 — Build your proposition
Why should customers choose you?
Step 4 — Set up your operating model
Determine the appropriate licensing, compliance and business structure for your market.
Step 5 — Configure your technology
Set up your branded platform and required integrations.
Step 6 — Launch
Start acquiring customers.
Step 7 — Expand
Add additional corridors and capabilities as demand grows.
This approach allows the business to validate its proposition before attempting to support dozens of markets.
When Does Building From Scratch Actually Make Sense?
Building your own platform isn't always the wrong decision.
It can make sense when:
- Technology is your core competitive advantage
- You have a substantial engineering organization
- You require highly specialized workflows
- You need complete ownership of the technology stack
- You have significant long-term infrastructure requirements
- You are prepared for ongoing development and maintenance
For some companies, owning every layer is strategically valuable.
But it comes with a corresponding investment in engineering, infrastructure, security, integrations and maintenance.
The decision should therefore be based on business strategy, not simply on whether building is technically possible.
When Does White-Label Make More Sense?
A white-label platform can be particularly attractive when:
You're entering the remittance market
You want to concentrate on establishing the business rather than creating an entire technology stack.
You already have customers
Your competitive advantage is distribution and customer relationships rather than software development.
You're launching a new corridor
You want to test a market without creating every component from zero.
You're an existing MTO
You want to modernize your customer experience and operational infrastructure.
You're expanding
You need technology that can support additional corridors and integrations.
The Real Question Isn't “Build or Buy”
The better question is:
“Where should we invest our competitive advantage?”
If your competitive advantage is technology, building can make sense.
If your competitive advantage is customers, corridors, partnerships, pricing or distribution, spending years rebuilding standard remittance infrastructure may not be the best use of your resources.
A white-label platform lets you choose a different starting point.
Instead of:
Idea → Build Everything → Integrate Everything → Test Everything → Launch
You can work toward:
Market → Business Model → Corridor → Technology → Launch → Customers → Scale
Build the Business, Not the Plumbing
Starting a money transfer business is already a significant undertaking.
You need to understand your market.
You need the appropriate regulatory and operating structure.
You need payment and payout relationships.
You need customers.
You need a strong value proposition.
You need trust.
You need an operational team.
Technology is essential — but it doesn't necessarily mean you need to build every component yourself.
The smarter approach for many businesses is to determine which technology capabilities are genuinely differentiating and which are infrastructure that can be provided through an established platform.
That's where a white-label remittance platform can become valuable.
What RemitSo Provides
RemitSo is a white-label remittance technology platform designed for businesses that want to operate their own branded money transfer business.
The platform provides technology across:
Customer Experience
Branded mobile and web experiences.
Operations
Administration, customer and transaction management.
Compliance
KYC, AML, sanctions and transaction-monitoring workflows.
FX & Pricing
Exchange-rate and fee management.
Payments & Payouts
Connectivity to supported payment and payout partners.
Infrastructure
Technology designed to support international transaction operations.
Your business remains focused on your customers, your market and your growth strategy.
Ready to Build Your Money Transfer Business?
You don't necessarily need to spend years building the infrastructure before you can start building the business.
Start with the market you understand.
Start with the corridor you believe in.
Build your brand.
And use technology that gives you a foundation to operate and grow.
Have a remittance business idea?
Let's discuss your market, corridor and launch plan.
Request a RemitSo Demo →
Looking to Automate Your Remittance Operations?
See how a white-label remittance platform can connect customer onboarding, compliance, transactions, FX, payments, payouts and back-office operations in one technology environment.
- White-label web and mobile apps
- Customer onboarding and KYC
- Transaction management
- FX and pricing
- Payment and payout connectivity
- Back-office operations
Frequently Asked Questions
Questions About Building a Remittance Platform
1. Can I build a remittance platform completely from scratch?
Yes. It is technically possible, but it requires significant development, integration, infrastructure, security and ongoing maintenance resources.
2. Is a white-label remittance platform the same as buying a money transfer licence?
No. Technology and licensing are separate considerations. Your licensing and regulatory obligations depend on your jurisdiction and operating model.
3. Can I launch with one remittance corridor?
Yes. A focused corridor can be a practical starting strategy, subject to your business, regulatory and partner requirements.
4. Can I use my own brand?
Yes. White-label technology is designed to allow the customer-facing experience to operate under your business brand.
5. Does RemitSo provide payment and payout connections?
RemitSo supports connectivity to payment and payout partners, subject to the applicable corridor, partner availability and onboarding requirements.
6. Is building from scratch always a bad idea?
No. If technology is your core competitive advantage and you have the resources to build and maintain the infrastructure, owning your stack may make strategic sense.
Money Transfer Platform With a Built-In Compliance Engine